Diamondback Energy’s $5 billion agreement to acquire Double Eagle’s Permian Basin holdings is more than another shale transaction—it is a test of how far consolidation can run while oil prices soften. The deal puts the spotlight directly on $FANG shares, integration execution and the valuation benchmarks that may shape the next round of Permian mergers and acquisitions.
For traders, the immediate issue is not simply the size of the transaction. It is whether Diamondback can translate a major expansion of its Permian position into a deal management presents as accretive, while convincing the market that operational integration will not dilute the strategic logic. Seeking Alpha reported the agreement as breaking merger news.
A landmark test for Permian consolidation
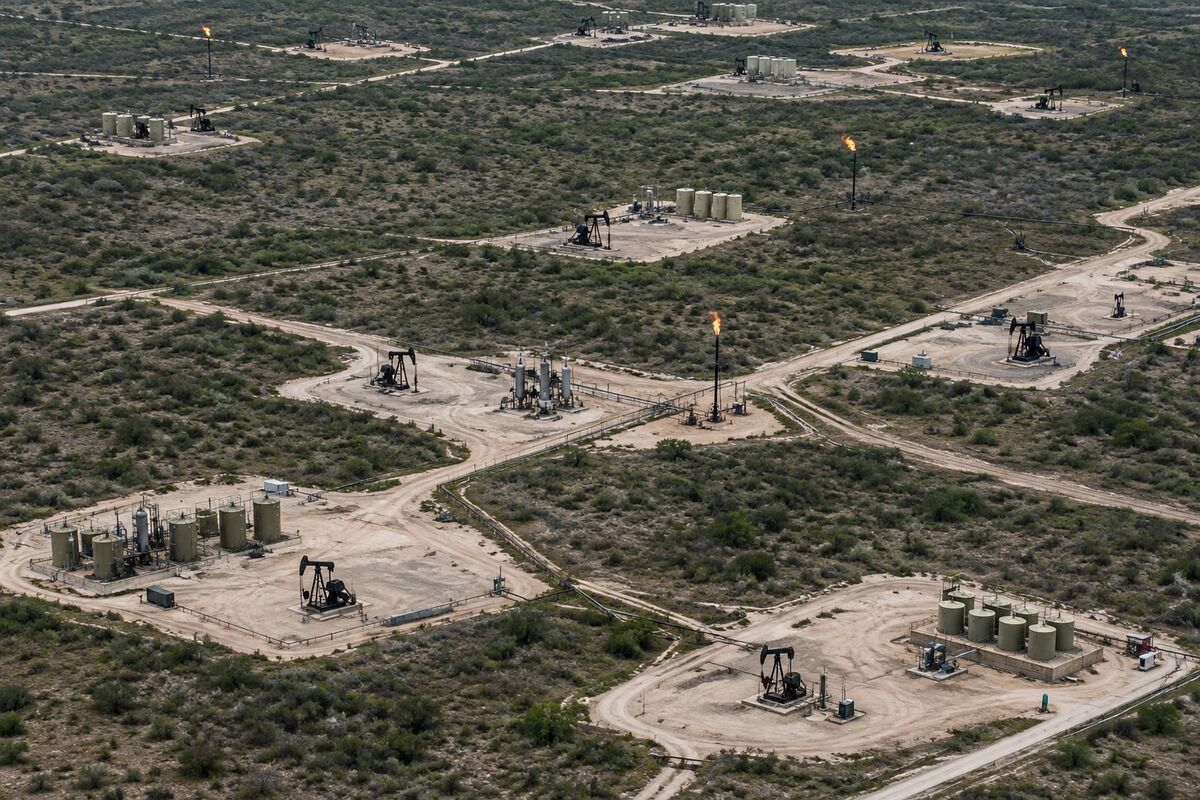
Diamondback confirmed the $5 billion agreement with Double Eagle, making the transaction one of the largest Permian consolidation deals of the year. That distinction matters. It signals that, even as oil prices soften, the industry’s consolidation playbook remains active at a scale capable of influencing how investors assess Permian-focused companies.
The transaction also reinforces the strategic importance of the Permian Basin. A deal of this size suggests that established operators continue to see value in assembling larger positions in the region. But size alone does not settle the investment case. The market will ultimately judge whether the acquisition strengthens Diamondback’s position without creating an integration burden that outweighs the expected benefits.
What traders may watch in $FANG
FANG shares are likely to be viewed through two competing lenses. The bullish interpretation is that Diamondback is using a large-scale acquisition to deepen its Permian footprint and potentially create greater operating scale. The skeptical interpretation is that a $5 billion transaction raises the execution stakes, particularly if management must integrate the acquired holdings during a period of softer oil prices.
The next important signal will be management’s characterization of the deal’s financial impact. Traders may focus on whether Diamondback describes the acquisition as accretive and how confidently it frames the integration plan. That commentary could influence whether the market treats the transaction as disciplined consolidation or as a more demanding test of balance-sheet and operating execution.
Ripple effects across shale
For competing Permian producers, Diamondback’s agreement may become a fresh reference point. It could encourage investors to revisit the strategic value of Permian assets and reassess how scale, basin exposure and consolidation potential are reflected in company valuations. It may also raise expectations that other operators could evaluate combinations or asset transactions of their own.
Still, the deal does not establish a blanket signal that every shale acquisition will receive the same reception. Oil prices are softening, and that backdrop can make investors more selective about transaction quality. A large announced deal may validate consolidation as a strategy while simultaneously raising the bar for proof that acquisitions can create value under less supportive commodity conditions.
The bottom line
Diamondback’s $5 billion purchase of Double Eagle’s Permian holdings is a consequential marker for the next phase of shale consolidation. Its significance extends beyond the two companies: the deal may shape how traders evaluate $FANG, how peers are benchmarked and how aggressively the sector pursues additional combinations. The decisive question is whether scale can translate into accretive economics and clean integration while oil prices remain under pressure.
Bull/Bear Verdict
Bull Case: The $5 billion Double Eagle transaction may strengthen Diamondback’s Permian position, reinforce the value of scale and support a broader consolidation thesis if management presents the deal as accretive.
Bear Case: Softening oil prices could make the $5 billion acquisition a tougher integration and valuation test, leaving $FANG shares vulnerable if management cannot demonstrate that the transaction will be accretive.