Rare-earth magnets are easy to overlook—until access to them becomes a legal and operational question. General Motors’ arbitration dispute with VAC puts that issue squarely on the radar for the auto industry, where specialized materials can matter far more than their cost suggests.
This is not merely a contract dispute. It is a reminder that electric-vehicle manufacturing depends on a chain of strategically important inputs, and that sourcing resilience may be tested well before a disruption appears in production figures. The reported arbitration followed General Motors’ termination of a rare-earth magnet supply agreement with VAC.
Why rare-earth magnets matter
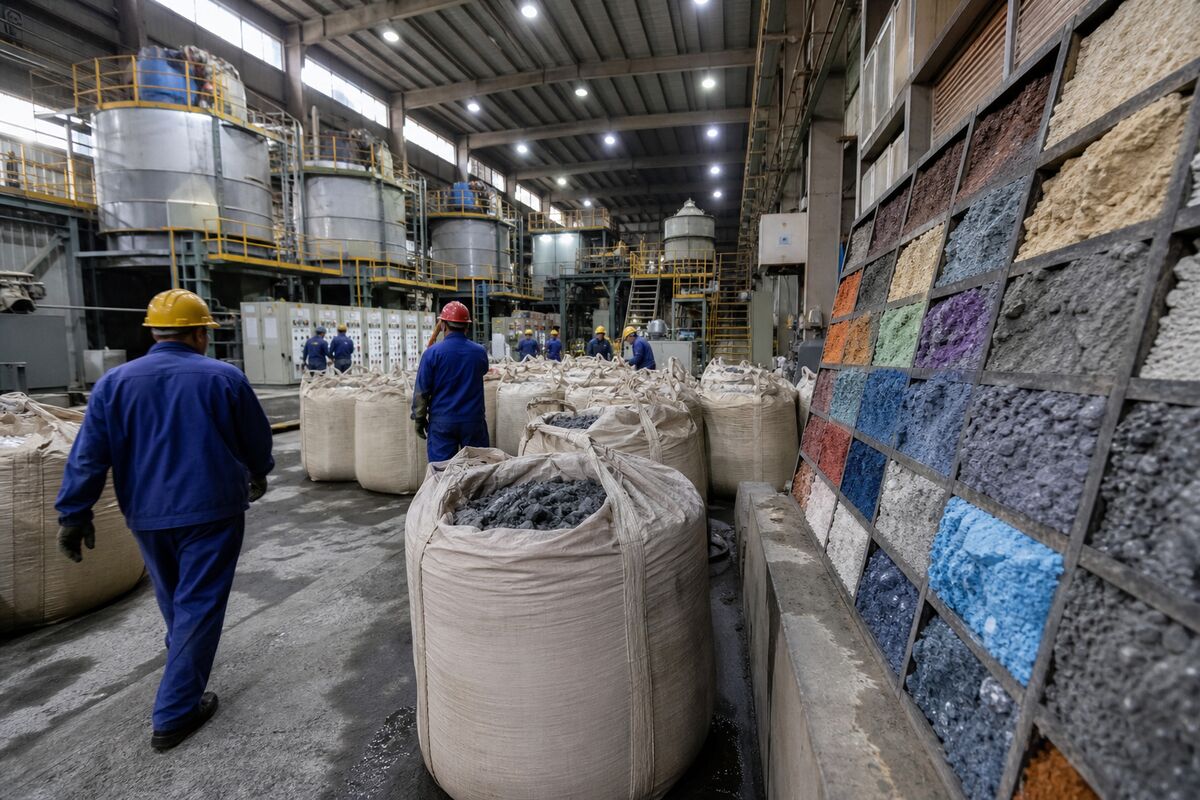
Rare-earth magnets are a critical input for electric vehicles and broader auto manufacturing. Their importance comes from the performance characteristics they bring to electric motors and other automotive systems, where compact size, strength and efficiency can be central to engineering decisions.
That makes the supply chain strategically sensitive. Automakers are not simply purchasing a generic commodity that can always be replaced without consequence. Materials used in vehicle platforms may be tied to design specifications, manufacturing processes and supplier qualification requirements. Any change in sourcing could therefore involve more than finding another vendor; it may require coordination across engineering, procurement and production.
The same logic extends beyond EVs. Rare-earth magnets can support applications across modern vehicle manufacturing, meaning supply considerations may affect a wider industrial ecosystem than electric powertrains alone. For automakers, the issue is not only whether material is available, but whether it can be sourced with the consistency and technical compatibility required by high-volume manufacturing.
The investor question is resilience
General Motors’ arbitration with VAC highlights a potential supply-chain and execution risk. The dispute does not establish a production impact, a replacement supplier or an eventual legal outcome. It does, however, draw attention to the practical challenge of managing critical inputs while vehicle programs continue to evolve.
Investors following NYSE-listed auto and industrial companies may monitor the matter because sourcing resilience has become an important part of execution. A company can have ambitious vehicle plans, but those plans still depend on reliable access to specialized materials and components. Supplier concentration, contract durability and the flexibility to qualify alternatives may all influence how exposed an automaker is when a commercial relationship changes.
The broader lesson is familiar to anyone who has watched industrial markets through multiple cycles: supply chains are often valued when they are functioning and scrutinized only when they are under strain. Rare-earth magnets may represent a small part of a vehicle’s total economics, yet their strategic role can be disproportionately large. GM’s dispute with VAC is therefore worth watching—not as evidence of a defined production problem, but as a case study in how sourcing decisions can become material to the investment narrative.
Bull/Bear Verdict
Bull Case: The arbitration could encourage greater attention to sourcing resilience, potentially strengthening how General Motors and other automakers manage critical rare-earth inputs for EV and broader vehicle manufacturing.
Bear Case: The dispute highlights execution risk around a material described as critical to EV and auto manufacturing, while the termination of the VAC agreement leaves sourcing resilience as an issue investors may continue to monitor.