JetBlue Airways’ latest quarter delivered a difficult headline for traders: the airline posted a bigger loss as elevated fuel costs pressured results. Yet management is presenting a more constructive operating narrative, arguing that margins are improving while the company works through a cost-cutting and premium-revenue strategy.
That tension puts $JBLU shares at the intersection of two competing forces. Near-term earnings reflect the damage from higher fuel costs, while the CEO’s commentary asks investors to focus on what the airline may look like after its current plan is further executed. For transport-sector traders, the question is whether operating improvements can gain traction before fuel pressure and demand uncertainty weigh more heavily on the business.
A wider loss, with fuel costs in the spotlight
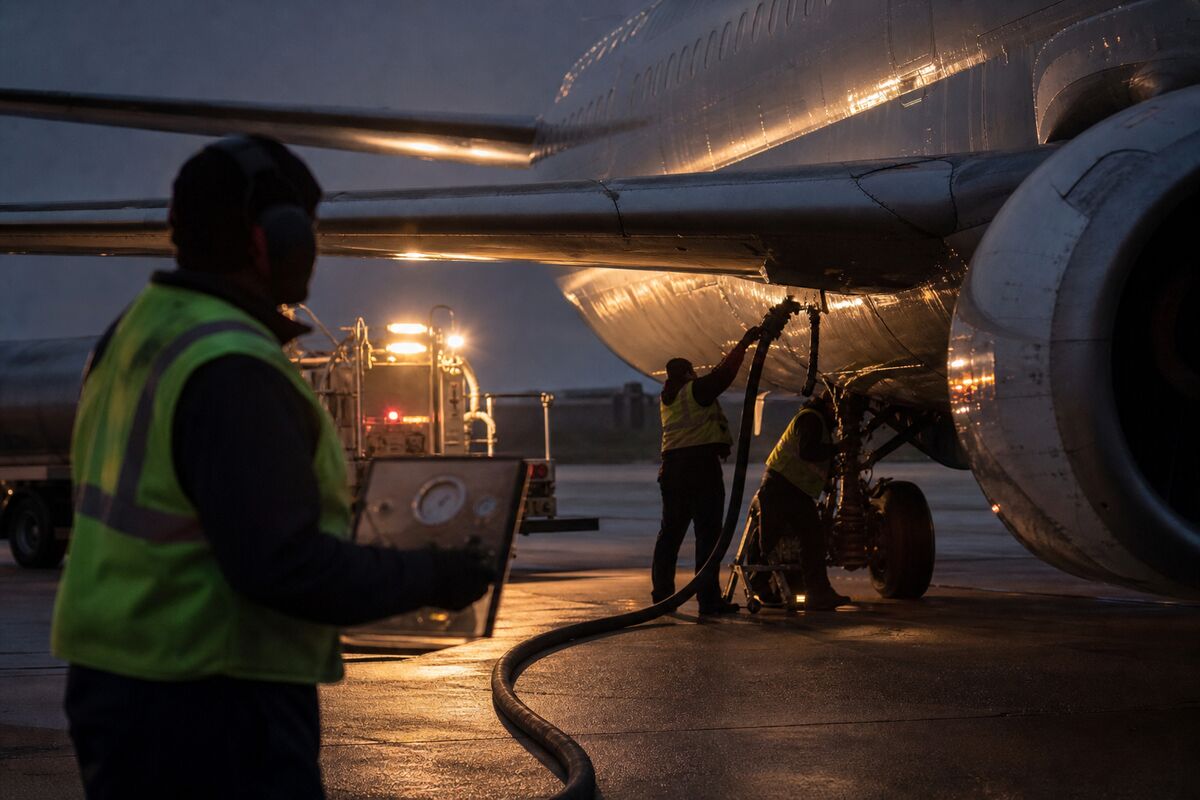
The most immediate data point is straightforward: JetBlue’s quarterly loss widened, and the company identified elevated fuel costs as a driver. That makes the result relevant beyond one airline. Fuel is a central cost pressure for carriers, so JetBlue’s performance offers a timely read-through on how energy expenses may affect airline margins heading into year-end.
The fuel-cost issue also complicates the market’s assessment of the company’s internal initiatives. A larger loss can obscure progress elsewhere in the operation, but it remains a material signal for traders evaluating the durability of any margin improvement. If fuel pressure persists, cost reductions may need to do more work simply to offset the external headwind.
Management is selling the execution story
JetBlue’s CEO emphasized that margins are improving as the airline executes a plan built around two levers: reducing costs and increasing premium revenue. The company is mid-execution, which means the strategy is not yet a completed restructuring or a fully realized earnings outcome. The market is being asked to evaluate progress while the plan is still unfolding.
That distinction matters. Cost cuts may support margins by lowering the expense base, while premium revenue could improve the economics of the seats and services JetBlue sells. Together, those initiatives suggest a path toward better operating performance if execution continues and customer demand remains supportive. They do not, however, remove the sensitivity of the airline model to fuel costs.
For $JBLU, the investment debate is less about one quarterly loss in isolation and more about whether improving margins can become visible enough to offset the pressure exposed by fuel.
What traders should watch next
The next phase of the story is execution. Traders may focus on whether JetBlue can continue reducing costs while building premium revenue, rather than treating management’s margin comments as a finished result. The company’s latest quarter shows that the plan is operating against a challenging cost backdrop.
- Fuel: Elevated fuel costs remain a direct pressure on the airline’s quarterly performance.
- Margins: Management says margins are improving, but the strategy remains mid-execution.
- Revenue mix: Premium revenue is a key part of the company’s plan to strengthen economics.
- Demand: JetBlue’s results provide a read-through on consumer travel demand heading into year-end.
The consumer-demand angle is equally important. Airlines depend on travelers continuing to spend on air travel, including higher-value offerings. If demand holds, premium revenue may give JetBlue more room to improve margins. If demand softens, the company could face a tougher environment for executing that part of its strategy while still absorbing elevated fuel costs.
The broader US airline sector may therefore view JetBlue’s quarter as a mixed signal: fuel costs are creating pressure, but management believes internal actions are beginning to improve margins. That combination leaves $JBLU shares tied closely to the credibility and pace of execution. The company has a plan, but the wider loss shows that the plan is being tested in real time.
JetBlue’s earnings discussion and management commentary are detailed in CNBC’s report on the quarter. For traders, the central issue remains whether cost cuts and premium revenue can advance faster than fuel-cost pressure erodes the benefit.
Bull/Bear Verdict
Bull Case: Improving margins, cost reductions and higher premium revenue could strengthen $JBLU’s operating profile if execution continues and consumer travel demand remains supportive.
Bear Case: The wider quarterly loss and elevated fuel costs suggest that external pressure may continue to outpace the benefits of JetBlue’s still-incomplete cost-cutting and premium-revenue plan.