
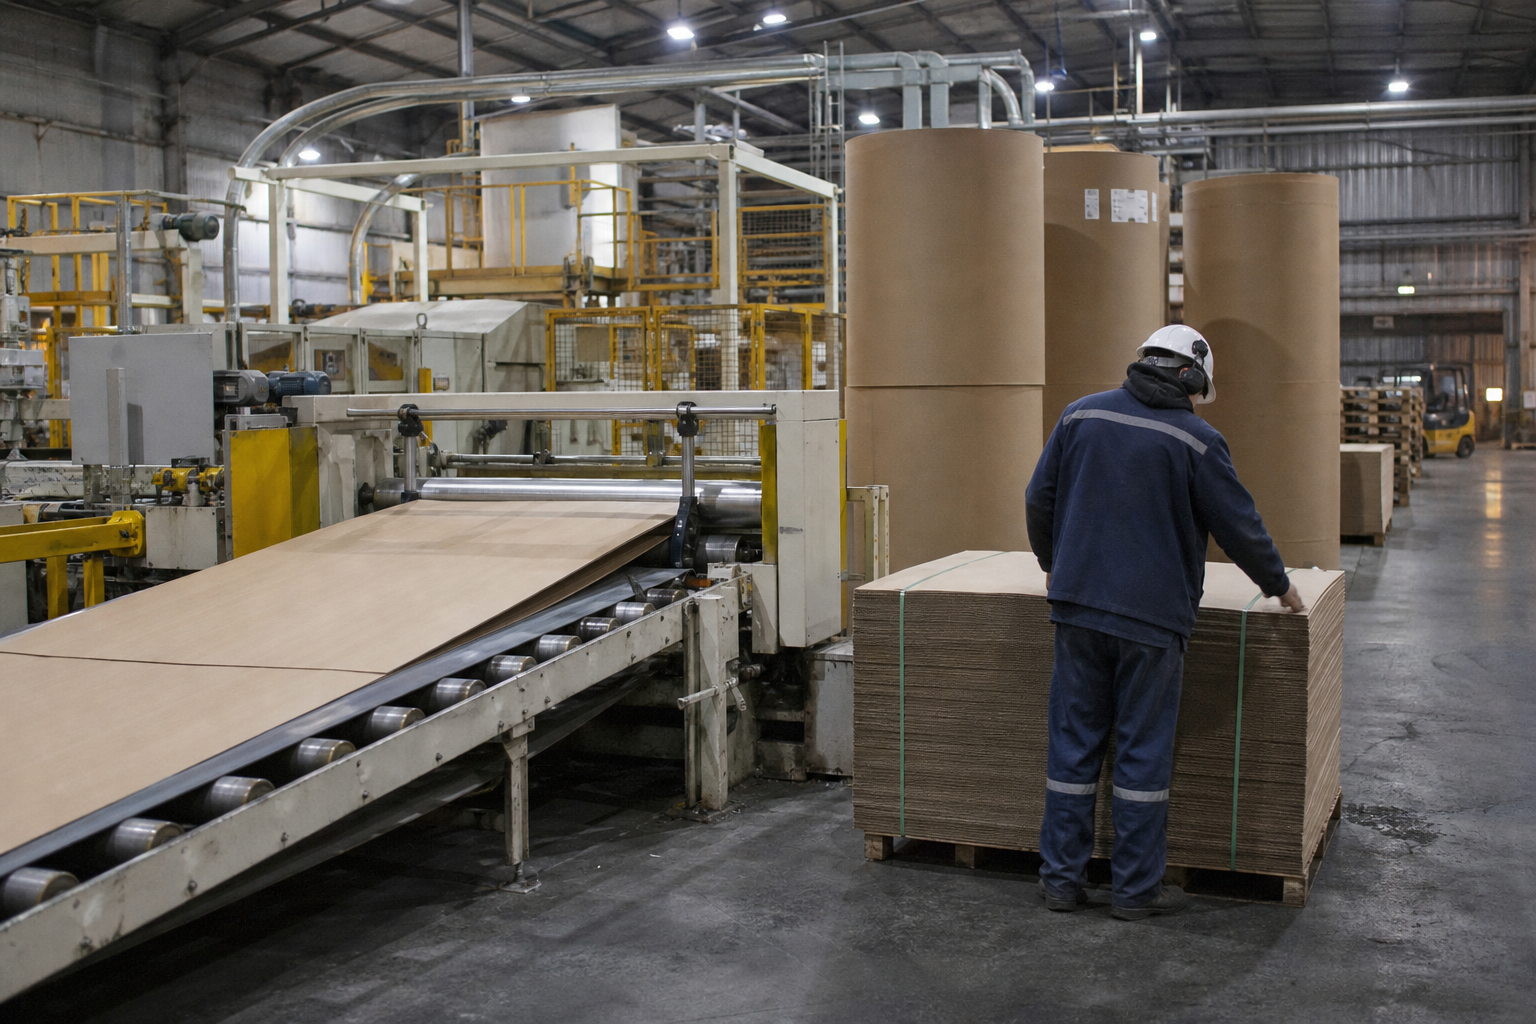
Smurfit WestRock is putting $420 million behind a bigger role in Latin American packaging. The NYSE-listed company has agreed to acquire Empresas CMPC’s Chilean containerboard business, turning a regional expansion story into a closely watched test of management’s capital-allocation judgment.
The deal matters beyond its headline price. For investors, it offers a fresh signal about how Smurfit WestRock sees long-cycle packaging demand, the strategic value of bolt-on acquisitions and the future shape of its Latin American footprint.
According to the reported transaction, Smurfit WestRock will pay $420 million for Empresas CMPC’s Chilean containerboard business. The announcement gives the company a tangible foothold in Chile while broadening its presence in Latin American packaging and containerboard.
A capital-allocation statement in corrugated fiber
Acquisitions are where corporate strategy leaves the conference-room whiteboard and meets the ledger. In this case, Smurfit WestRock is directing a significant sum toward an established packaging business rather than relying solely on organic expansion. That makes the transaction an important capital-allocation decision for a major industrial company listed on the NYSE.
The purchase may suggest that management sees strategic value in adding containerboard capacity and market presence in Chile. It may also indicate a preference for targeted, bolt-on transactions that extend an existing packaging platform rather than a move into an unrelated industry. The available details do not provide purchase-price multiples, financing terms, earnings forecasts or integration targets, so the strategic reading should remain separate from assumptions about near-term financial results.
Latin America becomes part of the investor conversation
Smurfit WestRock’s expanded Chilean presence could give investors another lens through which to evaluate its Latin American strategy. The acquisition broadens the company’s geographic packaging footprint, but the larger question is how management intends to build from that position over time.
Containerboard demand sits at the intersection of everyday shipping, industrial activity and consumer delivery. E-commerce is relevant to that discussion because more goods moving through delivery networks can require more corrugated packaging. Still, the transaction itself does not provide a forecast for e-commerce growth or establish a specific demand outlook. It is better viewed as evidence that packaging remains a market in which management sees value in securing additional operating presence.
That distinction matters. A $420 million acquisition can be strategically meaningful without automatically answering questions about returns, integration or future earnings. Investors may focus on whether the deal strengthens Smurfit WestRock’s regional position and whether management’s broader acquisition approach appears disciplined as more information emerges.
Why US packaging investors may watch closely
The announcement may influence how analysts and shareholders frame Smurfit WestRock’s growth narrative. Depending on subsequent commentary and market interpretation, the acquisition could become relevant to analyst price targets, company sentiment and expectations for the broader packaging sector.
Sector read-through may extend beyond Smurfit WestRock. International Paper, trading as $IP, and Packaging Corp. of America, trading as $PKG, are packaging peers that US investors could watch as they assess whether the transaction reflects a company-specific opportunity or a wider appetite for packaging assets.
For now, the clearest message is strategic rather than predictive: Smurfit WestRock has agreed to commit $420 million to expand its Chilean containerboard presence. Whether that decision becomes a durable contributor to the company’s investment case will depend on details not supplied in the announcement, including how the business is integrated and how management articulates the transaction’s role in its broader Latin American plan.
Bull/Bear Verdict
Bull Case: The $420 million acquisition may strengthen Smurfit WestRock’s Latin American packaging footprint and could signal disciplined interest in strategic bolt-on growth.
Bear Case: The deal’s strategic logic may be clear, but without supplied financing, integration or earnings details, investors cannot yet determine whether the $420 million commitment will translate into stronger financial performance.