
Wall Street ended Friday with a burst of relief: the S&P 500 gained 0.86% to close at 7,656.98, while the Dow Jones Industrial Average added 509 points. The rebound snapped the Dow’s four-day losing streak and gave investors a reason to believe the recent selling pressure had at least paused.
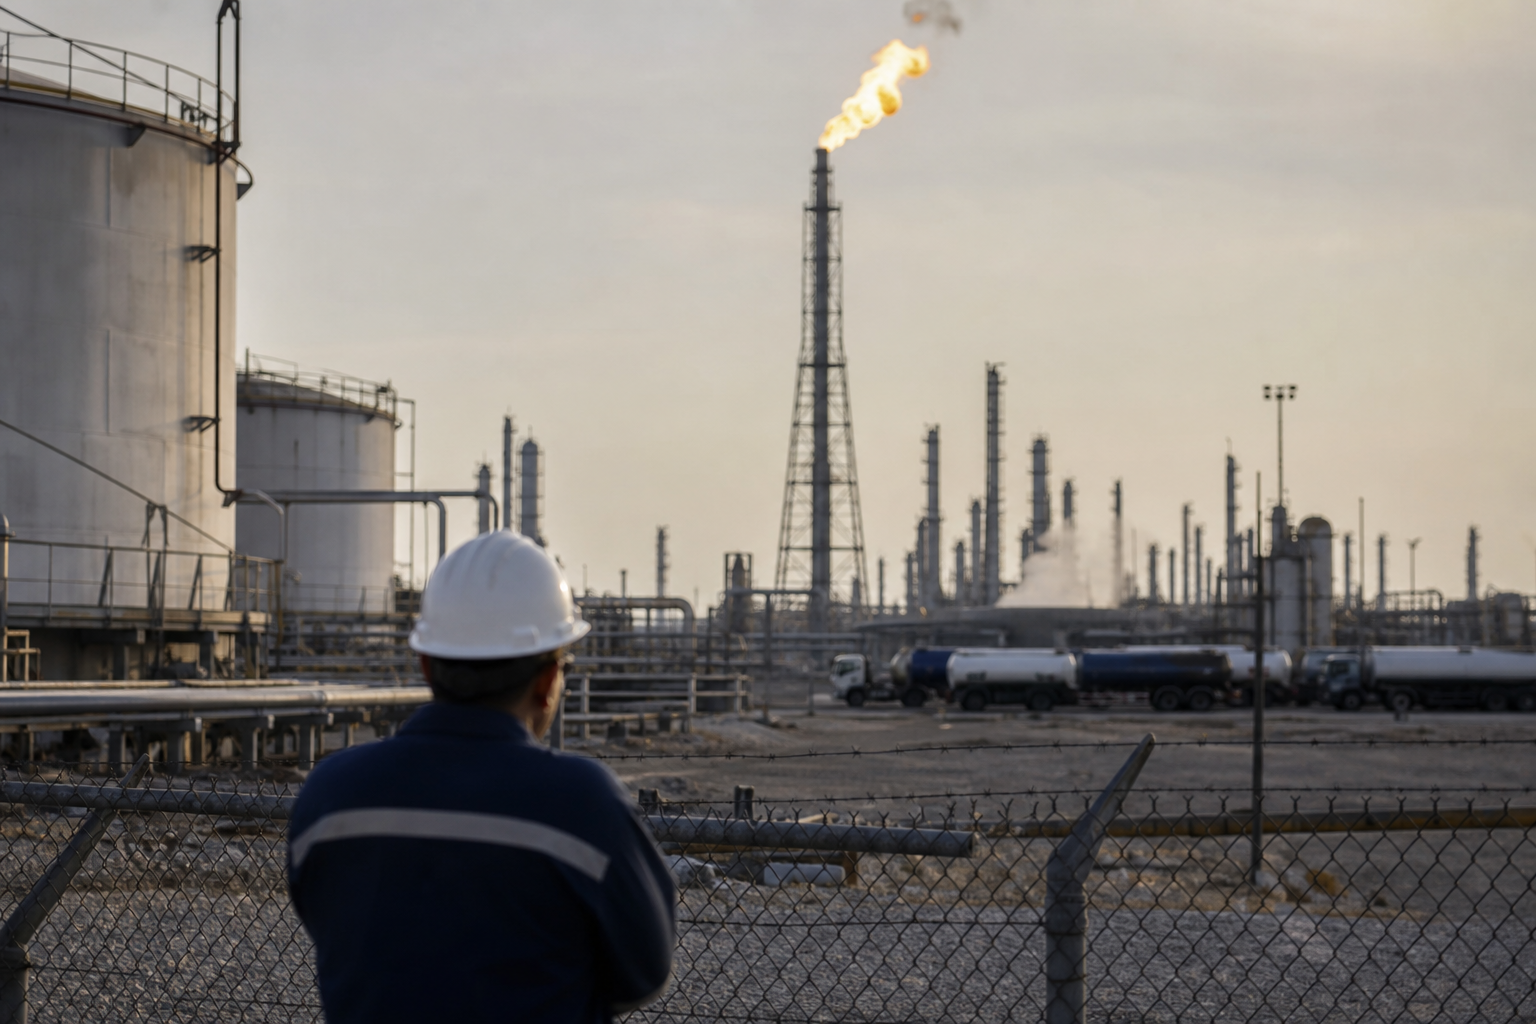
But Monday’s opening bell arrives with a less welcoming script. U.S. stock futures were pointing lower early in the session as investors weighed surging oil prices and elevated geopolitical tensions. The contrast leaves traders facing a familiar market question: was Friday the beginning of a recovery, or merely a breather before another bout of turbulence?
The Friday advance was broad enough to matter. The Nasdaq 100 gained 0.9%, helped by easing pressure from fuel prices and a pullback in long-dated Treasury yields from multi-year highs. That combination offered relief to rate-sensitive growth stocks, whose valuations can come under pressure when borrowing costs and bond yields rise.
Still, the market’s improved tone rests on a fragile foundation. Oil prices remain the most immediate swing factor because energy costs can travel through the economy in several directions. Higher fuel prices may revive inflation concerns, complicate expectations around interest rates and make investors more sensitive to every move in the bond market.
That creates a difficult backdrop for equities. Friday showed that stocks can rebound when fuel-price pressure eases and Treasury yields retreat. Monday is testing whether that support can endure when oil prices are moving higher again. The answer may not arrive in the first headline or the first futures reading; it could emerge only after investors see whether early weakness attracts buyers or gathers momentum.
Geopolitics adds another layer of uncertainty
The reported U.S.-Iran geopolitical conflict gives the oil market an additional source of tension. When geopolitical risk and energy prices rise together, investors may become less willing to treat a single strong session as proof that market conditions have stabilized.
That does not erase Friday’s gains. The S&P 500’s close at 7,656.98, the Dow’s 509-point increase and the Nasdaq 100’s 0.9% advance remain concrete evidence that buyers returned to the market. But the weaker Monday futures point to a more skeptical opening, with investors reassessing whether the rebound can withstand a fresh dose of oil and geopolitical anxiety.
For U.S. equity traders, the key issue is follow-through. A market that absorbs early pressure and reverses higher could suggest that Friday’s rebound still has traction. A deeper slide after the opening bell could indicate that the rally was more fragile than it appeared. Either way, choppy trading may be the defining feature as investors balance easing Treasury yields against renewed concern over fuel prices and conflict.
The bond market will remain part of that equation. Long-dated Treasury yields easing from multi-year highs helped create room for rate-sensitive growth stocks on Friday. If that relief persists, it may help cushion equity sentiment. If oil-driven inflation worries push yields back toward recent highs, the market could again face pressure from both sides: higher energy costs and less favorable financial conditions.
That is why Monday’s session matters beyond its opening move. The market has already demonstrated it can rebound sharply after a difficult stretch. Now it must contend with a more complicated test, one involving oil volatility, Treasury yields and the reported U.S.-Iran conflict. Until investors see clearer follow-through, Friday’s recovery may look less like a new chapter and more like a market pausing with one eye on the exits.
For additional market context, Trading Economics tracks the U.S. stock market, while Yahoo Finance reported on the Monday market setup. CNBC also provided coverage through its markets reporting.
Bull/Bear Verdict
Bull Case: Friday’s 0.86% S&P 500 gain to 7,656.98, the Dow’s 509-point advance and the Nasdaq 100’s 0.9% rise may indicate that easing fuel-price pressure and lower long-dated Treasury yields can still support a rebound.
Bear Case: Weaker Monday futures, surging oil prices and the reported U.S.-Iran geopolitical conflict could revive inflation concerns and keep trading choppy, limiting the rebound’s follow-through.