MasTec is making a decisive bet that the next phase of infrastructure investment will reward specialized execution. The company has entered a definitive agreement to acquire Murphy Corporation for approximately $1.25 billion, adding one of the largest and most respected mechanical contractors in the United States to its platform.
For shareholders of $MTZ, the transaction is more than a corporate expansion story. It is a signal that MasTec sees strategic value in owning capabilities tied to mission-critical construction, including the facilities and systems supporting data centers and industrial operations. The deal also puts a large number on the broader consolidation theme running through infrastructure and mechanical-contracting services.
MasTec’s announcement identifies Murphy as a leading mechanical contractor serving mission-critical end markets. Murphy was founded in 1907, giving the business a long operating history in a specialized segment where experience, execution and credibility can matter as much as physical scale. The company is described as one of the largest and most respected mechanical contractors in the United States.
That positioning is central to understanding the transaction. A mechanical contractor serving mission-critical markets is not simply providing a general construction service. Its role is connected to facilities where construction quality, coordination and reliability are particularly important to the customer’s operations. MasTec’s stated rationale places Murphy inside that strategic framework rather than treating it as an unrelated addition.
The headline figure is approximately $1.25 billion. That is a substantial commitment for MasTec, and it makes the acquisition’s strategic fit the key issue for investors and traders. The question is not merely whether MasTec is adding revenue-producing capacity. The more important question is whether Murphy gives the company a stronger position in specialized markets where customers require technical expertise and where project execution can influence the usefulness of the finished facility.
Why specialized mechanical contracting matters
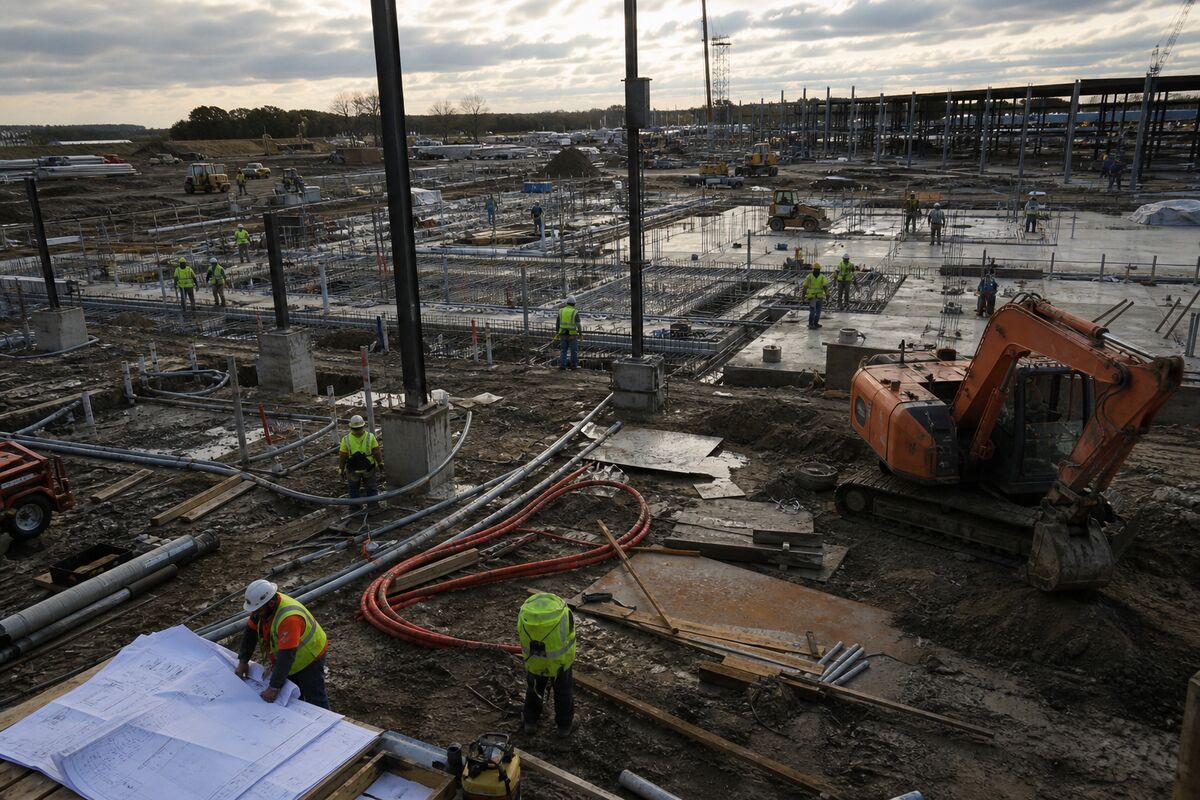
Data centers and industrial facilities represent the kind of projects that can make specialized mechanical capabilities strategically important. These facilities depend on complex physical infrastructure, and the mechanical scope is a central part of delivering an operating site. As demand associated with such projects grows, contractors with established expertise may become increasingly valuable to larger infrastructure platforms.
That does not mean every acquisition in the sector will create the same result. It does suggest why MasTec would pursue a company whose identity is closely connected to mission-critical end markets. Murphy brings a focused mechanical-contracting position, while MasTec brings a broader infrastructure strategy. The combination may allow MasTec to participate more directly in projects where specialized construction capabilities are a competitive differentiator.
The transaction therefore fits a familiar pattern in infrastructure markets: larger platforms seek to assemble a broader set of services, while specialized operators become acquisition targets because their capabilities can be difficult to replicate quickly. For a buyer, acquiring an established contractor may offer a more direct path into a market than building a comparable operation from the ground up. For the seller’s business, joining a larger platform may provide access to a wider infrastructure organization.
Those are strategic possibilities, not guaranteed outcomes. The announcement establishes the agreement and the approximate purchase price, but it does not establish that the transaction will automatically produce operating benefits. The value of the deal will depend on how effectively MasTec integrates Murphy while preserving the expertise and reputation that made the mechanical contractor attractive in the first place.
A meaningful test of MasTec’s infrastructure strategy
For MasTec shareholders, the acquisition’s scale makes discipline important. A $1.25 billion transaction can influence how the market views the company’s capital allocation and its willingness to expand through acquisitions. The purchase indicates that management is prepared to commit significant resources to a business tied to mission-critical construction rather than limiting its strategy to incremental expansion.
The fit is also clear at the market-theme level. MasTec is acquiring a company described as one of the largest and most respected mechanical contractors in the US, and the target serves end markets associated with data centers and industrial facilities. That combination gives $MTZ a more visible connection to specialized construction demand and to the infrastructure requirements of those facilities.
Still, the market will likely distinguish between strategic logic and execution. The transaction’s rationale rests on Murphy’s expertise, its established position and the demand profile of its end markets. If those characteristics remain intact within MasTec, the acquisition may strengthen the company’s infrastructure platform. If integration weakens the qualities that differentiate Murphy, the strategic case becomes less compelling.
The deal also highlights the broader consolidation cycle in infrastructure and mechanical contracting. As projects become more specialized and customers seek contractors capable of handling complex requirements, scale can become an advantage. Larger companies may be better positioned to offer multiple capabilities, while established specialists may command attention because they bring market knowledge and technical depth.
That consolidation theme should not be confused with a simple race for size. In mechanical contracting, the quality of the acquired platform matters. Murphy’s founding in 1907 and its stated standing in the US market are relevant because they point to an operating history and reputation that MasTec is attempting to add to its own infrastructure strategy. The deal is consequently about capability as much as it is about consolidation.
The bottom line for the market
MasTec’s Murphy agreement is a clear strategic statement. The company is directing approximately $1.25 billion toward a specialized contractor serving mission-critical end markets at a time when data centers and industrial facilities are central to the infrastructure discussion. That gives the deal a logical connection to a major construction trend without requiring investors to look beyond the facts of the announcement.
For traders, the transaction creates a focused debate around strategic expansion, acquisition execution and the market’s appetite for infrastructure consolidation. For long-term shareholders, the central issue is whether Murphy’s specialized position can strengthen MasTec’s broader platform without diluting the qualities that made the target attractive.
The deal is not a conclusion; it is a test. MasTec has identified mechanical contracting and mission-critical construction as areas worthy of a major commitment. The next measure will be whether that commitment translates into a more capable infrastructure business while preserving Murphy’s established standing.
More details on the transaction and Murphy’s role in mission-critical markets are available in MasTec’s announcement and this market report.
Bull/Bear Verdict
Bull Case: The approximately $1.25 billion Murphy acquisition may strengthen $MTZ’s infrastructure strategy by adding one of the largest and most respected US mechanical contractors, with exposure to mission-critical markets tied to data centers and industrial facilities.
Bear Case: The deal’s scale makes execution critical, and the strategic rationale could weaken if MasTec cannot preserve the specialized expertise and established market reputation Murphy has built since its founding in 1907.