When high-beta technology stocks begin to wobble, investors often look for steadier ground in the aisles of the grocery store. Utz Brands’ latest quarterly release offers one such checkpoint: the U.S. branded salty-snack manufacturer has reported results for the third fiscal quarter ended September 27, 2026.
That makes $UTZ more than another earnings-season data point. As a small-cap growth and value consumer-staples equity, Utz sits at the intersection of two investor searches: the potential durability associated with everyday food products and the growth expectations attached to a smaller company. The central question is whether its quarterly report supports that defensive appeal—and what it says about the pricing power of branded snacks.
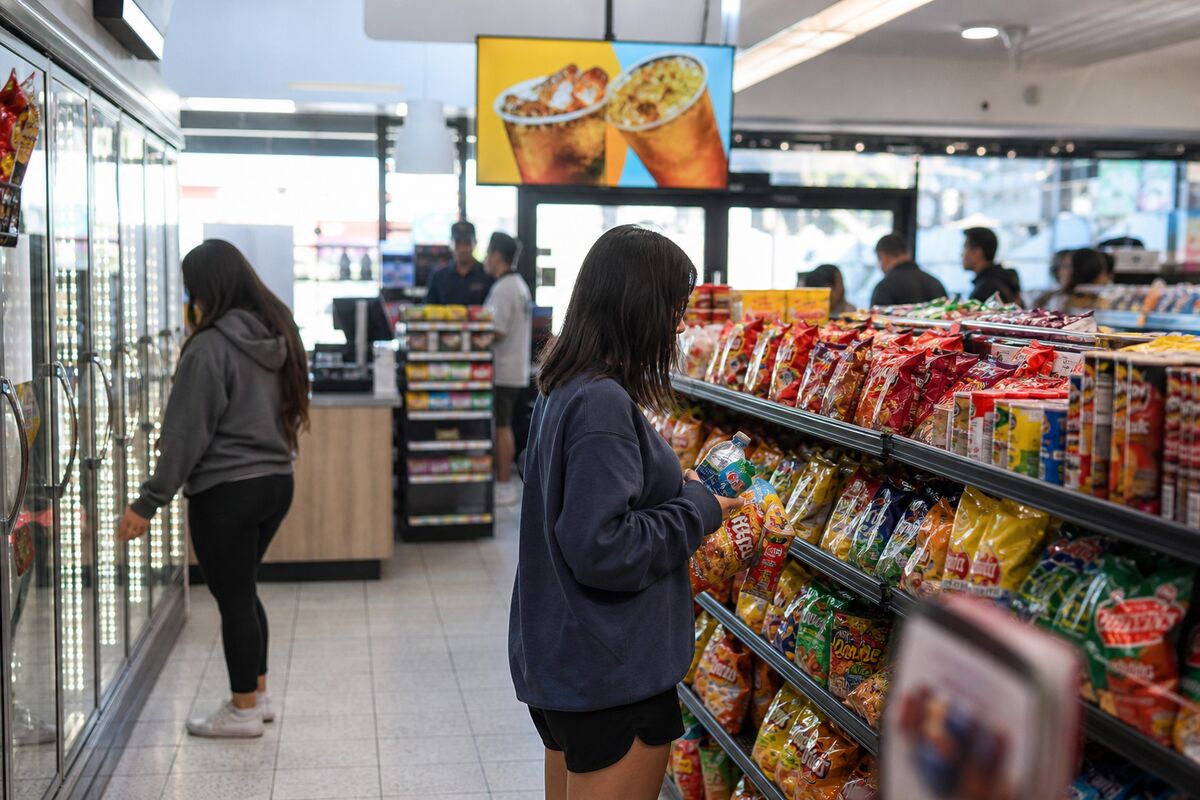
Utz describes itself as a leading U.S. manufacturer of branded salty snacks, a business built around products that occupy a familiar place in household shopping baskets. That familiarity can matter when markets become unsettled. Consumers may continue purchasing established snack brands even as they reassess larger discretionary commitments, giving the sector a different rhythm from technology shares whose valuations and sentiment can be more sensitive to market swings.
Still, “defensive” is not a magic label. A consumer-staples company must navigate the balance between what shoppers will pay and what they are willing to buy. For Utz, the third-quarter results provide the latest lens through which investors can examine that balance. The company’s quarterly release is therefore relevant not only to shareholders, but also to anyone tracking how branded food businesses are holding up amid a broader flight from high-beta technology stocks.
What the quarter means for the snack aisle
The report does not turn Utz into a defensive stock by category alone. Instead, it gives the market a fresh occasion to test whether the company’s branded portfolio can remain relevant as investors scrutinize consumer resilience. Pricing power, in particular, is best judged through the company’s reported quarterly details rather than through the consumer-staples designation itself.
That distinction matters. A recognizable snack brand may have room to adjust prices, but the durability of that power depends on how shoppers respond and how the business performs alongside those changes. The third-quarter results place that question squarely before investors without making the answer automatic.
A small-cap twist on a defensive theme
Utz’s classification as both a small-cap growth and value consumer-staples equity gives the report an unusual market role. It is not simply a large, mature household-products name offered as a shelter from volatility. Nor is it purely a high-growth technology story. The company represents a more nuanced proposition: a branded consumer business whose everyday products may appeal to investors seeking resilience while its smaller-cap profile keeps growth and execution in focus.
For now, the significance of the quarter lies in the conversation it advances. As technology-led market pressure redirects attention toward consumer businesses, Utz’s September 27 results offer a timely measure of how investors are evaluating branded snacks, pricing power and the meaning of defensiveness in a small-cap stock.
Bull/Bear Verdict
Bull Case: Utz’s third-quarter results, covering the period ended September 27, 2026, may reinforce the appeal of a leading U.S. branded salty-snack maker as investors seek consumer-staples exposure during a technology-led selloff.
Bear Case: The small-cap profile of $UTZ means the third-quarter report may not, by itself, settle whether branded-snack pricing power is durable or whether the stock can deliver both growth and defensive resilience.